

Objecting to tax penalties in the UAE follows a specific legal process and cannot normally be handled simply by submitting a general complaint to the Federal Tax Authority (FTA).
Depending on the nature of the decision and the stage reached in the dispute, the taxpayer may need to proceed through several formal stages, beginning with a Request for Reconsideration before the Federal Tax Authority, followed, where appropriate, by an objection before the Tax Disputes Resolution Committee (TDRC) and then an appeal before the competent court.
Each stage has its own legal requirements and deadlines. Missing a statutory deadline or failing to satisfy an admissibility requirement may prevent the taxpayer from progressing to the next stage.
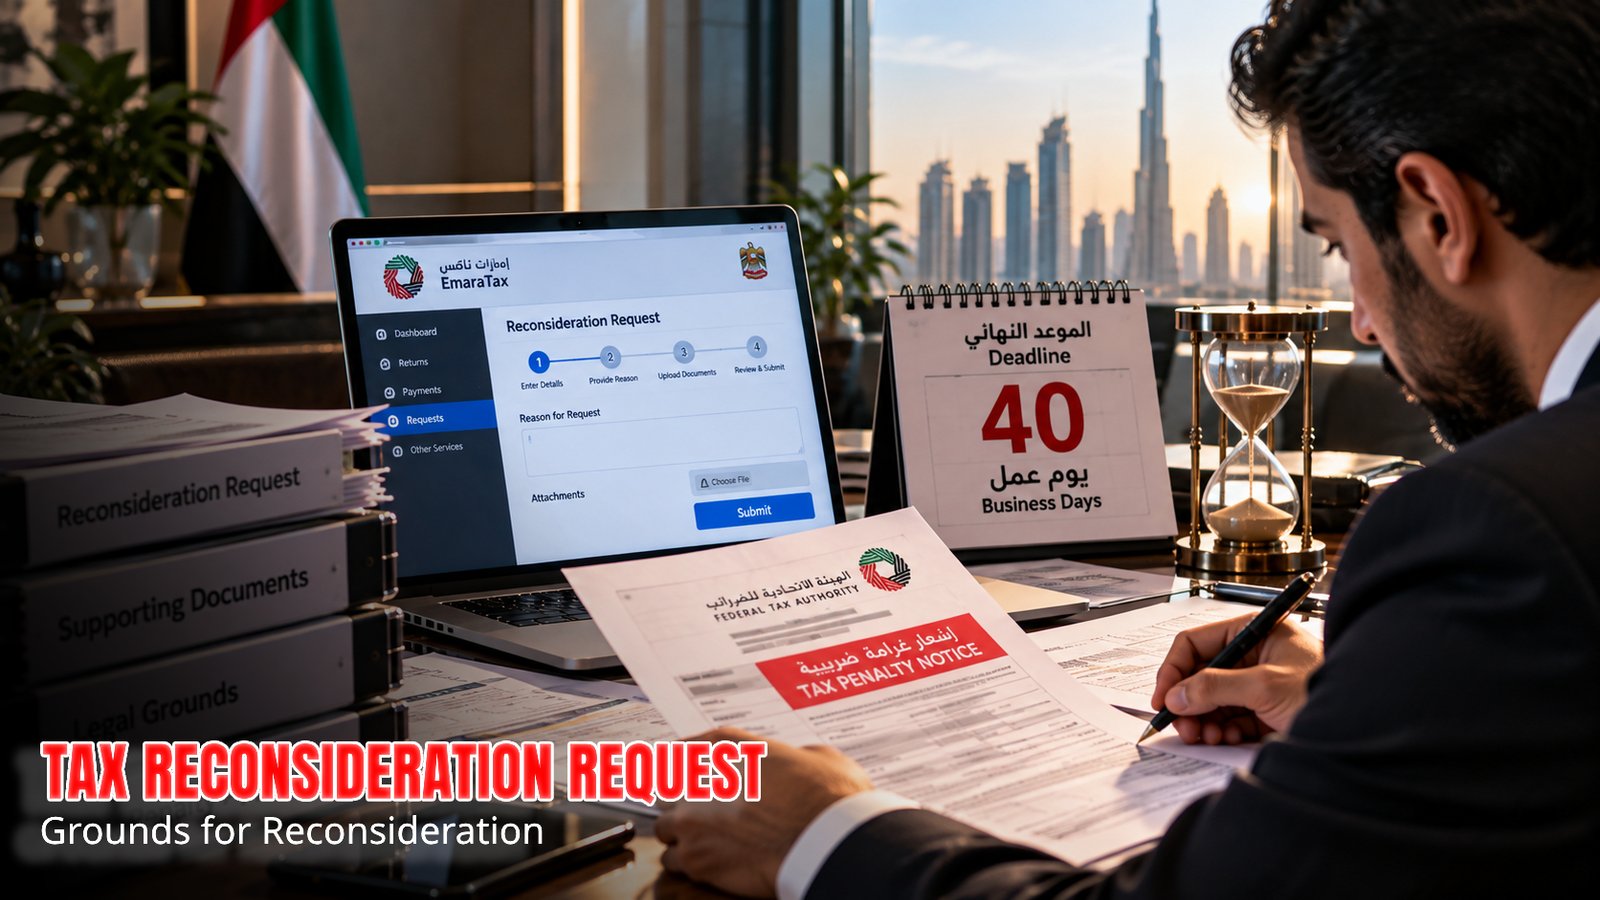
The UAE Federal Tax Authority currently confirms that a reconsideration request is submitted through EmaraTax, and the request must generally be filed within 40 business days from notification of the FTA’s decision.
For this reason, taxpayers who receive an administrative penalty assessment or another tax decision should review the decision promptly rather than waiting until the deadline approaches.
What Is a Tax Penalty in the UAE?
A tax penalty is an administrative sanction imposed under UAE tax legislation where a taxpayer fails to comply with a legal or procedural tax obligation.
Depending on the applicable tax law and the circumstances, penalties may relate to matters such as:
- Failure to register for tax when required.
- Late submission of a tax return.
- Failure to submit required information.
- Failure to maintain appropriate tax records.
- Incorrect tax declarations.
- Failure to pay tax when due.
- Other violations of tax procedures or obligations.
The existence of a penalty does not necessarily mean that the taxpayer has no legal grounds to challenge it.
The taxpayer may have grounds to argue that:
- The penalty was imposed incorrectly.
- The relevant legal conditions were not satisfied.
- The amount was calculated incorrectly.
- The underlying facts were misunderstood.
- The taxpayer has supporting evidence that was not properly considered.
- The relevant procedural requirements were not followed.
What Is the First Step in Challenging a Tax Penalty?
The first step depends on the nature of the FTA decision and the applicable tax dispute procedure.
A taxpayer challenging an FTA decision may generally submit a Request for Reconsideration to the Federal Tax Authority.
Article 27 of the UAE Tax Procedures legislation allows a person to request reconsideration of an FTA decision, in whole or in part, provided that the request is justified and satisfies the applicable conditions. The statutory deadline is generally 40 business days from the date of notification of the decision.
The FTA’s current online service also confirms that the reconsideration request is submitted through EmaraTax and that supporting documentary evidence should be provided to establish the factual and legal grounds of the request.
What Is a Request for Reconsideration?
A Request for Reconsideration is a formal legal request asking the Federal Tax Authority to reconsider an official decision issued against the taxpayer.
It is different from a general complaint or inquiry.
The FTA expressly states that only official decisions issued by the Authority concerning the taxpayer are eligible for reconsideration. General inquiries, complaints, and requests for clarification are not treated as reconsideration requests.
The request should therefore clearly identify:
- The decision being challenged.
- The date of notification.
- The disputed penalty or tax amount.
- The legal grounds for challenging the decision.
- The factual circumstances.
- Supporting documents and evidence.
- The specific relief requested.
What Is the Deadline for Filing a Reconsideration Request?
The general statutory deadline is 40 business days from the date on which the taxpayer is notified of the FTA decision.
This deadline is extremely important.
A taxpayer should not calculate the deadline simply by counting calendar days.
The applicable working-day rules should be considered when calculating the deadline.
The FTA also confirms that a person may request an extension of the reconsideration deadline in accordance with the applicable rules and FTA Decision No. (1) of 2025.
Because missing the deadline can affect the taxpayer’s ability to challenge the decision, the notification date should be documented immediately.
How Do You Submit a Reconsideration Request?
The FTA’s current procedure is conducted electronically through the EmaraTax platform.
The general process is:
- Log in to the EmaraTax account.
- Access the Taxable Person Profile.
- Select Other Services.
- Select Reconsiderations.
- Choose New Request.
- Enter the required information.
- State the factual and legal grounds for the request.
- Upload supporting evidence.
- Submit the request.
The FTA currently states that documentary evidence supporting the factual and legal grounds should be attached.
What Documents Should Be Attached to a Reconsideration Request?
The supporting documents depend on the nature of the dispute.
They may include:
- The FTA decision.
- Tax assessment documents.
- Administrative penalty assessment.
- Tax returns.
- Tax invoices.
- Accounting records.
- Bank statements.
- Contracts.
- Correspondence with the FTA.
- Previous submissions.
- Evidence supporting the taxpayer’s explanation.
- Legal opinions or tax advice where relevant.
The evidence should not simply be uploaded as a collection of unrelated documents.
It should be organised so that each document supports a specific factual or legal argument.
What Should a Strong Reconsideration Request Contain?
A strong request should explain why the FTA decision should be changed, rather than merely stating that the taxpayer disagrees with the penalty.
The request should ideally contain:
1. Identification of the Decision
Clearly identify the FTA decision being challenged.
2. Relevant Facts
Explain what happened in chronological order.
3. Legal Grounds
Identify the legal provisions supporting the taxpayer’s position.
4. Evidence
Connect each important factual argument to the relevant supporting document.
5. Explanation of the Error
Explain precisely why the penalty or decision should be cancelled, reduced, or otherwise reconsidered.
6. Specific Request
Clearly state the relief requested from the FTA.
How Long Does the FTA Take to Decide a Reconsideration Request?
The FTA currently states that it may take up to 45 business days to respond to a completed reconsideration request, and that the Authority may extend the specified period where permitted.
This should be distinguished from the taxpayer’s 40-business-day deadline for submitting the reconsideration request.
In other words:
40 business days → taxpayer’s filing deadline
Up to 45 business days → FTA’s stated processing period for the completed request
The applicant is also notified of the FTA’s decision after it is issued.
What Happens If the FTA Rejects the Reconsideration Request?
If the taxpayer disagrees with the FTA’s decision on reconsideration, the dispute may be taken to the Tax Disputes Resolution Committee (TDRC), subject to the applicable statutory requirements.
The FTA confirms that a taxpayer may dispute a reconsideration decision before the Tax Disputes Resolution Committee.
The objection is not simply a continuation of the original reconsideration request.
It is a separate procedural stage requiring compliance with its own admissibility requirements.
What Is the Tax Disputes Resolution Committee?
The Tax Disputes Resolution Committee (TDRC) is the specialised committee responsible for considering eligible tax disputes between taxpayers and the Federal Tax Authority.
The Committee examines the objection and gives the parties an opportunity to respond to the arguments and evidence presented by the other side.
The FTA explains that objections are submitted to the Department of Tax Dispute Resolution Committees at the Ministry of Justice through the relevant online objection system.
What Is the Deadline for Objecting Before the TDRC?
The objection must generally be submitted within the statutory period following notification of the FTA’s reconsideration decision, or following the expiry of the applicable period for the FTA to issue its decision where the Authority has not issued one.
The current legal framework generally provides a 40-business-day period for this stage, subject to the applicable legislation and rules governing extensions.
This means that a taxpayer should continue monitoring deadlines even after submitting a reconsideration request.
Submitting the first request does not eliminate the need to calculate the deadline for the next stage.
Must the Tax Be Paid Before Going to the TDRC?
Payment requirements are an important admissibility issue.
Under the applicable tax dispute framework, the taxpayer generally must settle the tax amount connected with the objection before proceeding to the Tax Disputes Resolution Committee, subject to the applicable statutory provisions.
The official UAE Government platform confirms that payment of the relevant taxes and penalties is required before proceeding to the committee under the applicable tax procedures framework.
Because payment requirements can affect whether an objection is admissible, the taxpayer should assess the amount, payment status, and applicable legal requirements before filing.
What Documents Are Required for an Objection Before the TDRC?
The objection should be supported by the relevant documentation.
The FTA identifies information and documents including:
- Applicant’s name and details.
- Address.
- Summary of the subject of the objection.
- Requests made by the applicant.
- Supporting documents.
- Electronic notification details for the legal representative or tax agent.
- Other documents relating to the grounds of objection.
The objection should also explain why the FTA’s reconsideration decision should not stand.
How Does the TDRC Deal With the Objection?
The Committee reviews the objection and gives the parties an opportunity to respond to the submissions made by the other side.
The FTA states that the Committee issues its decision within 20 business days from submission of the objection, subject to the applicable extension rules.
The Committee’s decision may then be subject to judicial appeal depending on the value of the dispute and the applicable legal requirements.
Can a TDRC Decision Be Appealed?
Yes, subject to the applicable legal conditions.
The taxpayer and the FTA may have a right to challenge a TDRC decision before the competent court.
However, the right to appeal and the effect of the TDRC decision may depend on the value of the dispute and other statutory requirements.
The UAE tax dispute framework provides special treatment for disputes involving amounts of AED 100,000 or less, while disputes exceeding that threshold may be subject to judicial appeal within the applicable deadline.
Therefore, the taxpayer should not assume that every TDRC decision can be appealed in exactly the same manner.
What Are the Most Common Mistakes When Objecting to Tax Penalties?
Several mistakes can weaken or even prevent a tax objection.
Missing the Deadline
The most serious mistake is failing to submit the request within the applicable statutory period.
Filing a General Complaint Instead of a Reconsideration Request
A general complaint does not necessarily replace the formal reconsideration procedure.
The FTA expressly distinguishes official decisions eligible for reconsideration from general inquiries, complaints, and clarification requests.
Providing Arguments Without Evidence
A legal argument should be supported by relevant records and documents whenever possible.
Failing to Address the Actual Reason for the Penalty
A taxpayer should explain why the specific legal or factual basis for the penalty is incorrect.
Submitting an Incomplete File
Missing documents may make it difficult for the authority or committee to assess the taxpayer’s position.
Ignoring Payment Requirements
Failure to satisfy applicable tax-payment requirements may affect the admissibility of a later objection.
Using Incorrect Legal Provisions
Tax disputes often depend on the precise wording and application of the relevant tax legislation.
Using an outdated provision or applying the wrong tax law may weaken the argument.
Can Tax Penalties Be Waived or Reduced?
In certain circumstances, UAE tax legislation provides mechanisms through which administrative penalties may be reconsidered, waived, or reduced, depending on the applicable law and the facts of the case.
However, a taxpayer should not assume that every penalty can automatically be cancelled.
The appropriate route depends on:
- The type of penalty.
- The reason for imposing it.
- The taxpayer’s conduct.
- The applicable legislation.
- Available evidence.
- Whether the relevant legal conditions for relief are satisfied.
A separate Administrative Exception Request may also be available in certain VAT and Excise Tax matters, but the FTA expressly states that this service cannot be used simply to request an exception from paying taxes, registering for VAT or Excise Tax, or waiving/reducing penalties.
Is It Possible to Challenge a Tax Penalty Without Being VAT Registered?
The availability of a reconsideration request is not necessarily limited to persons who are registered for VAT.
The FTA currently states that a person seeking reconsideration does not necessarily have to be a taxable person registered with the FTA or have an appointed tax agent.
The actual eligibility depends on the nature of the FTA decision and the applicable tax legislation.
Can a Tax Agent or Legal Representative File the Reconsideration Request?
Yes.
The FTA currently states that the concerned person may submit the request directly, and it also accepts requests submitted by an appointed Tax Agent or Legal Representative.
Where the taxpayer is part of a Tax Group, the Representative Member should submit the request where the applicable rules require this.
Why Is Legal Representation Important in Tax Penalty Disputes?
Tax penalty disputes are not simply accounting disagreements.
They can involve:
- Interpretation of tax legislation.
- Procedural requirements.
- Calculation of penalties.
- Evidence.
- Notification dates.
- Filing deadlines.
- Tax assessments.
- Administrative decisions.
- Payment requirements.
- Committee procedures.
- Judicial appeal.
A legal adviser can help determine the correct procedural route, identify the legal grounds, organise the evidence, calculate deadlines, and present the taxpayer’s position in a structured manner.
How Can Legal Consultant Mohammed Jasem Help?
Legal Consultant Mohammed Jasem assists individuals and companies in the UAE with tax disputes and challenges to administrative tax penalties.
Legal support may include:
- Reviewing the FTA decision.
- Analysing the tax penalty.
- Reviewing the notification and applicable deadlines.
- Examining tax records and supporting evidence.
- Preparing a Request for Reconsideration.
- Preparing an objection before the TDRC.
- Reviewing payment and admissibility requirements.
- Preparing legal arguments and supporting documents.
- Following up on the dispute.
- Assessing the possibility of judicial appeal.
The appropriate legal strategy depends on the type of tax, the nature of the penalty, the FTA decision, the evidence, and the procedural stage reached by the taxpayer.
Frequently Asked Questions
How Do I Object to a Tax Penalty in the UAE?
The taxpayer generally begins by submitting a formal Request for Reconsideration to the Federal Tax Authority within the applicable statutory deadline. If the dispute remains unresolved, the taxpayer may proceed to the Tax Disputes Resolution Committee, subject to the applicable conditions.
How Long Do I Have to Request Reconsideration?
The general statutory deadline is 40 business days from notification of the FTA decision. An extension may be available in accordance with the applicable rules.
Can I Challenge an FTA Decision Online?
Yes. The FTA’s current reconsideration service is available through the EmaraTax platform.
What Happens If the FTA Rejects My Reconsideration Request?
You may be able to file an objection before the Tax Disputes Resolution Committee, provided that the statutory conditions and deadlines are satisfied.
Do I Have to Pay the Tax Before Going to the TDRC?
Payment of the relevant tax amount is generally an important admissibility requirement for proceeding with an objection before the Committee, subject to the applicable legal provisions.
How Long Does the TDRC Take to Decide?
The FTA states that the Committee issues its decision within 20 business days from submission of the objection, subject to applicable extension provisions.
Can I Appeal a TDRC Decision?
A TDRC decision may be subject to judicial appeal depending on the value of the dispute and the applicable legal requirements.
Can a Tax Agent File the Reconsideration Request for Me?
Yes. The FTA accepts reconsideration requests submitted by an appointed Tax Agent or Legal Representative, subject to the applicable requirements.
Can a Tax Penalty Be Cancelled?
It may be possible depending on the type of penalty, the facts, the applicable legislation, and the evidence supporting the taxpayer’s position. Cancellation is not automatic.
Legal Consultant Mohammed Jasem – Tax Dispute and Penalty Assistance
Legal Consultant Mohammed Jasem provides legal assistance in UAE tax disputes, including challenges to FTA decisions and administrative tax penalties.
Services may include reviewing FTA decisions, assessing legal and procedural grounds, preparing reconsideration requests, preparing objections before the Tax Disputes Resolution Committee, reviewing supporting evidence, and assessing available judicial remedies.
Because tax disputes are subject to strict statutory deadlines and procedural requirements, obtaining legal advice at an early stage can help protect the taxpayer’s procedural rights.
Conclusion
Objecting to tax penalties in the UAE requires more than simply informing the Federal Tax Authority that a penalty is unfair.
The taxpayer must follow the applicable legal procedure, identify the correct decision being challenged, calculate the statutory deadline, provide appropriate evidence, and present clear factual and legal grounds.
The process may begin with a Request for Reconsideration before the Federal Tax Authority, followed where appropriate by an objection before the Tax Disputes Resolution Committee, and potentially judicial proceedings before the competent court.
The most important practical point is to act within the applicable deadline.
A taxpayer who receives a tax penalty should therefore review the decision promptly, preserve the relevant records, assess the legal grounds for challenging the penalty, and determine the appropriate procedural route before the statutory deadline expires.
Legal Disclaimer
This article is provided for general legal and educational information only and does not constitute legal advice or a legal opinion regarding any specific tax dispute.
UAE tax legislation, administrative procedures, FTA decisions, and applicable regulatory requirements may be amended from time to time. The applicable law and procedure should therefore be reviewed based on the date of the relevant decision and the specific facts of the case.
For a case-specific assessment, it is recommended to consult Legal Consultant Mohammed Jasem and provide the relevant FTA decision, tax records, penalty assessment, correspondence, and supporting documents.
Comments are closed